Why Home-Based Child Care Deserves a Place in the Capital Markets
Home Grown was founded in 2019 by a group of funders galvanized by a simple fact: nearly 7 million young children in the United States receive their early education in a home, not a center, and that care is almost invisible in policy debates, research, and investment. They built a national funders collaborative focused on improving quality and access in home-based child care, and recruited Natalie Renew to be the founding director.
Five or six months later, the pandemic arrived, and the fledgling initiative found itself building relationships with roughly 2,500 providers overnight, including partnering with Reinvestment Fund to design an emergency grant fund for home-based providers in 13 communities across the country including Philadelphia early in the pandemic.
By then, Renew had spent almost 20 years trying to get the right resources, the right people, and the right funders into the same room at the same time. She started in child welfare, moved into out-of-school-time work in Philadelphia, and led the early childhood education practice at Public Health Management Corporation, where she oversaw contracts spanning Head Start, city and state pre-K, child care, and home visiting.
The Most Common Care, the Least Seen
Six years later, Renew, argues that home-based care is the mainstay of the American child care system and the part of it that capital markets have almost entirely ignored.
The numbers back her up. Home-based settings are the most common form of care for infants and toddlers: 30% are cared for in licensed homes, compared with 12% in centers, according to Home Grown’s own research.
Most home-based providers offer care during nontraditional hours 60% of the time, compared with 8% of centers, filling gaps for parents working overnight shifts or long commutes that a center built around an 8 a.m. to 3 p.m. schedule cannot serve. Yet just 1% of Head Start seats and 1% of pre-K seats sit inside home-based settings.
Underwritten Out
“Very few CDFIs lend to these caregivers and providers,” Renew said. Community development financial institutions may offer technical assistance or re-grant philanthropic dollars, but few home-based providers are offered loans or take on the debt directly
Renew sees two reasons why. First, it comes down to loan size. Home-based providers usually need microloans, which don’t conform well to typical CDFIs lending practices. Second, traditional underwriting standards were built for, say, charter schools or housing developers and fail to recognize what a home-based business actually looks like.
She offers an example. A provider in San Francisco has held a license to serve 14 children for 20 years, maintains a waiting list, and pays $4,500 per month in rent. By any reasonable measure, her business is stable and in demand. “She can’t get a mortgage. She can’t get a business loan,” Renew said. The hurdle is that “our field is not viewed as credible,” which result in a lack of loan products built for businesses run out of a home. The metrics that would normally establish loan worthiness—longevity, a waiting list, steady revenue—are not being applied to her at all.
That exclusion, Renew argues, gets read backward as a deficiency in the providers themselves. She rejects that reading outright.
“These women take $30,000 dollars a year in revenue,” she said. “They successfully meet the learning, growing and care needs of six or more children and their families. And they are able to feed their own families.”
No consultant, she added, could stretch that budget as far. The low revenue is not poor management. It is the predictable result of a system that underpays a workforce that chose to serve low-income families, and then penalizes it for the choice.
This is the argument at the center of Renew’s work, and it also speaks to risk. Providers are frequently described as risk-averse, as though caution were a personal trait rather than a rational response to conditions.
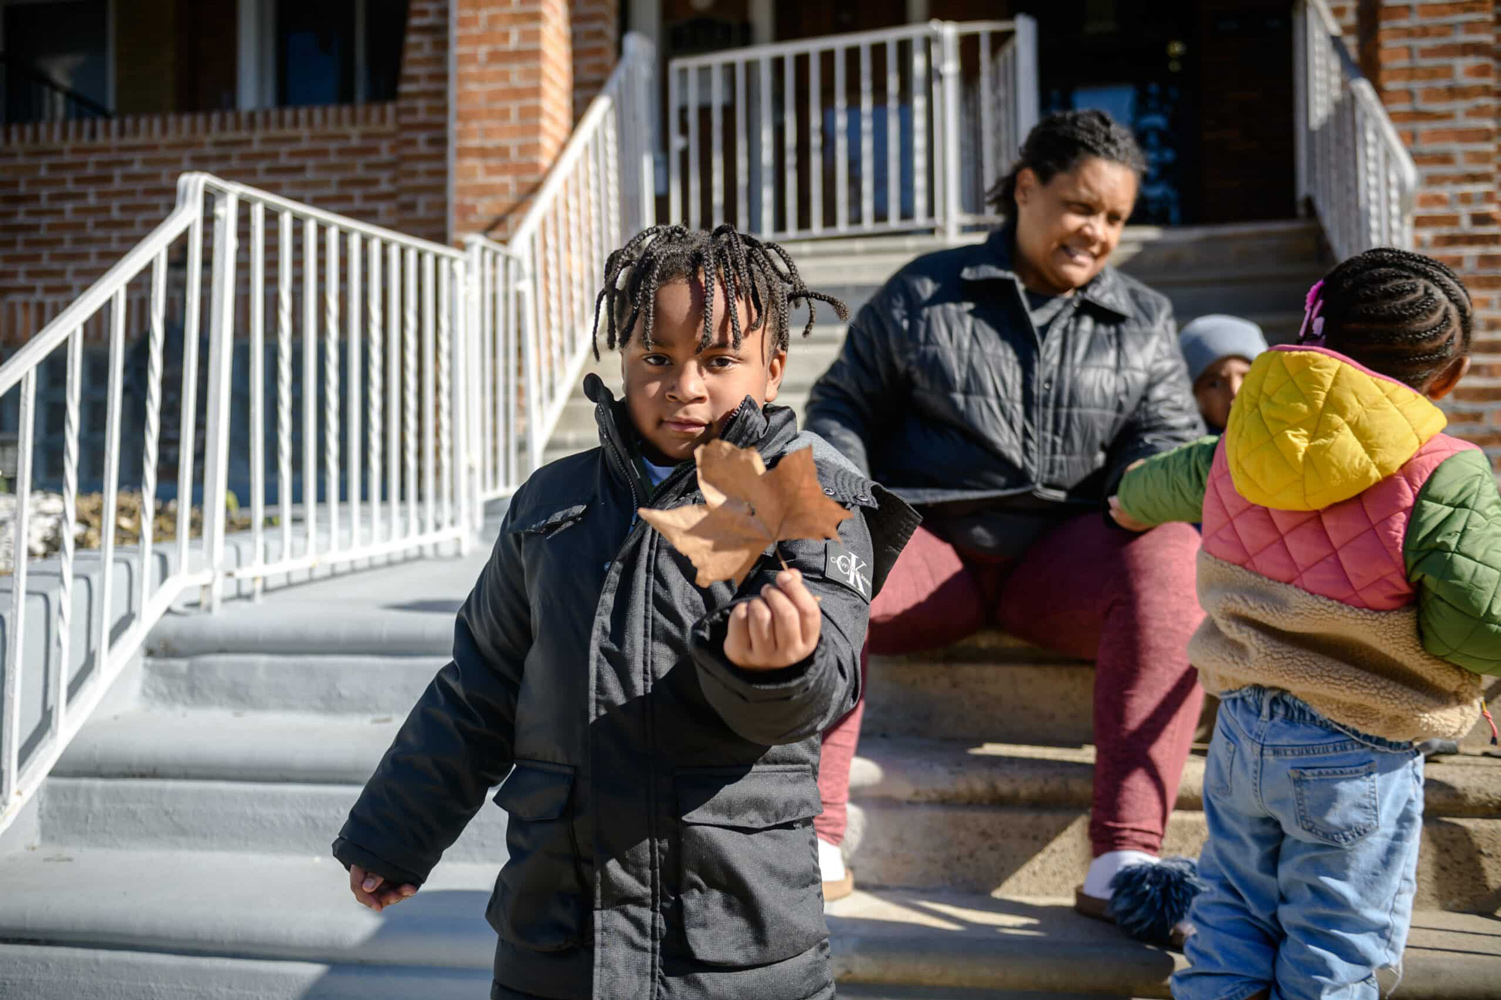
A group of children at a Home Grown location.
In New Mexico, where the state now reimburses providers who expand, Renew has watched providers seek capital at rates she has not seen before. “Providers are not stupid,” she said. “It’s because they understand this landscape to be largely scarce,” and they will not take on debt they cannot repay in an environment engineered to make repayment hard.
Renew’s broader policy agenda runs on a similar logic. Home Grown organizes its work around three areas: building power for home-based providers so they have a seat at the tables where program rules get written, shifting a narrative that treats home-based care as an asset rather than a deficit, and reimagining the public systems, from the Child and Adult Care Food Program (CACFP), to pre-K, to Head Start, that currently leave these providers out.
Renew resists any solution built around a single delivery model. Families’ needs shift as children age, jobs change, and households grow, and a system that funds only centers or only homes leaves families choosing between options rather than moving between them as their circumstances change.
Investing in Trusted Providers
That gap is exactly what Reinvestment Fund’s own recent work in the sector is supporting.
In Montgomery County, Maryland, Reinvestment Fund now administers the Montgomery County ECE Facility Loan Program, a $4 million initiative offering forgivable loans of up to $74,000 and zero-percent-interest loans of up to $300,000, available to and created specifically with home-based child care providers as well as small center-based programs in mind.
Built as a public-private partnership, the county provides funding to support local child care businesses serving residents. This is a key innovation in how local government uses economic development to back early educators. The Facility Loan Program has currently funded 14 loans, with work expected to create nearly 200 new child care openings.
Loan forgiveness is not automatic. Providers must stay open and licensed for five years and complete ongoing business training. The program was also built to solve the cash-flow problem Renew describes: providers rarely have the upfront capital to start a renovation before reimbursement arrives. Reinvestment Fund’s Managing Director of ECE, LaToshia DeVose, and her team structured the loan disbursements specifically so providers are not asked to front costs they cannot cover.
In Philadelphia, Reinvestment Fund’s SEED Fund takes a longer view of the same problem.
The program combines grant dollars with financial coaching focused on retirement planning, mirroring the same wealth-building work for home-based child care businesses Renew advises on through Home Grown’s Thriving Providers Project, which delivers guaranteed income to stabilize provider earnings.
Reinvestment Fund’s programs are geographically bound to Montgomery County and Philadelphia, not the national capital markets access Renew is hoping for.
But together they are a working answer to her core challenge: a family child care home underwritten and treated like the small business it is, with real loan products and repayment terms, and customized technical assistance. Whether that model will travel beyond two markets is an ongoing endeavor.
Anchors in a Changing Neighborhood
There is a placemaking argument buried inside this, too, one Renew reaches for without much prompting.
A provider she visited recently in North Philadelphia described watching her block change around her as investor-owned housing replaced longtime residents.
“Her neighbors don’t pick up the trash outside their house,” Renew said. “They aren’t homeowners with a commitment to building a neighborhood in the same way.” Meanwhile, the provider still walks children to the park every day.
In neighborhoods reshaped by rapid turnover, a home-based provider is sometimes the last permanent resident on the block, a resident who will remain committed to the neighborhood’s vitality.
Who Pays, and Who Gets In
Renew’s own read on the future is unambiguous: universal child care, publicly funded, that includes home-based providers and every family who wants to use one, regardless of immigration status. She wrote as much earlier this year, describing 2026 as a policy window in which the problem, the solution, and the political appetite have finally converged.
The open questions, in her view, are no longer whether universal child care arrives but who pays for it and who is allowed inside it.
The fact that prompted a group of funders to build Home Grown in 2019—that millions of children are cared for in homes the rest of the system does not see—has not changed. A handful of geographically bound programs and emerging pilots across the country will not close the capital gap on their own, but they show what a CDFI underwriting a family child care home as a real small business can look like.
Scaling that model, with broader capital support and innovative government partners on terms that recognize what home-based providers have already proven they can do with far less, is what Renew is spending this policy window trying to build.